
Financial Wellness for Healthcare Professionals
An interview with Joel Swanson, President and CEO of Associated Healthcare Credit Union, conducted by Minnesota Physician, an independent medical business journal.
Please tell us how Associated Healthcare Credit Union (ACHU) got started and how it has changed over the years?
AHCU’s story began in 1953 when five employees at Miller Hospital in St. Paul, where the Minnesota History Center sits today, decided to pool their resources and create a credit union to help health care workers support one another financially. For example, when a hospital employee needed a few hundred dollars for an unexpected expense, medical bill, household need or to buy a car to get to work. Smaller unsecured loans less than $400 were typically not offered by big banks, where health care workers felt they were being treated as second-class citizens.
Seventy-three years later, the scale and complexity of financial needs have changed dramatically, but that basic idea remains relevant. Today, it might be helping a physician coming out of residency with significant student debt qualify for a home based on a signed employment contract. Or it might be preparing them with the financial literacy to manage the stress of their new high debt-high income financial status. Over the years, employee credit unions serving Blue Cross and Blue Shield of Minnesota, Children’s Minnesota and HealthEast joined AHCU, which now serves more than 12,000 members throughout the Twin Cities. It has evolved from a single-hospital employee credit union into an institution focused on the broader spectrum of Minnesota health care professionals, their careers and their families.
You have an unusual window into the financial lives of Minnesota health care professionals. What are you seeing today that is surprising?
The original problem was access to fair financial services. Today the challenge is designing financial services around careers that don’t always follow conventional financial assumptions. Minnesota has a world-class health care ecosystem. It is an enormous and growing part of Minnesota’s economy. Health care and social assistance alone employed nearly 557,000 Minnesotans in 2025. Yet the people doing that work can still be financially stretched. And that isn’t confined to lower-wage employees. The pressures differ by career stage and profession. For example, the median medical-school debt for the class of 2025 was $215,000. The Association of American Medical Colleges (AAMC) puts the median four-year cost of medical school for the class of 2026 at about $298,000 at public schools and $408,000 at private schools.
Furthermore, this year the Federal Reserve reported that 59% of adults had experienced at least one major unexpected expense during the prior year, with vehicle repair or replacement the most common at 30%. A $1,000 surprise means something different to a surgeon, a resident, a nurse, a medical assistant or a customer service representative. But financial friction can affect all of them. Student debt can delay home ownership, childcare can affect the shifts someone can accept, or a car repair can affect whether someone can reliably get to work. Financial resilience boils down to having realistic options to withstand unexpected expenses or income disruptions that meet the needs of someone in the health care industry.
Health care is widely regarded as a financially secure profession. How accurately does that reflect what you see?
There’s often a misconception that health care is one economic category, experiencing higher incomes and financial status. A physician finishing fellowship, however, or an established specialist, an RN, a medical assistant or a nursing assistant can all work in the same building and have dramatically different financial lives. The latest Minnesota Department of Employment and Economic Development report shows Twin Cities vacancy data that puts the median wage being offered for open RN positions at about $39.41 an hour, compared with $19.93 for nursing assistants and $21.29 for medical assistants.
Physicians, comparatively, have much higher earning potential but begin those earning years relatively late and with substantial education debt; the AAMC’s median debt figure data mentioned earlier offers perspective. Most financial institutions and products ignore that unique income trajectory. In addition, in Minnesota, we have robust communities of insurers, med tech/med device, pharmaceutical, wellness — and a myriad of support and ancillary services, many of them innovators in their field. The roles in those organizations come in all shapes and sizes.
Personal approaches are necessary because income and financial wellness don’t mean the same thing. What matters is the entire balance sheet; income, debt, savings, housing costs, family responsibilities and the predictability of that income. Financial security means much more than public perception and can vary widely within every industry sector.
There’s often a misconception that health care is one economic category.
What are some of the biggest challenges you see for those working in the health care industry today?
Health care leaders regularly cite burnout and workforce shortages as major challenges. Financial stress isn’t necessarily the primary cause of health care burnout — staffing, workload, administrative burden, workplace culture and the emotional demands of caring for others are well-documented factors. But financial pressure can make each of those pressures harder to manage.
If someone is already exhausted but can’t afford to reduce hours, take unpaid time off, address a health issue, arrange childcare or absorb an unexpected expense, they have fewer options for finding relief.
For example, a stark finding from Mercer’s 2026 health care industry survey was that 35% of workers say the cost of care limits their ability to seek care for themselves or their families, compared with 28% of workers overall. There’s a real irony when people who spend their careers delivering health care are themselves struggling with the affordability of accessing it.
Are traditional financial products and underwriting models keeping pace with today’s health care careers?
Not always. Financial underwriting tends to look backward because that’s how risk models were designed. Health care careers can sometimes require looking forward. Consider a physician finishing residency who has a signed employment contract but doesn’t yet have 12 months of attending-level income. Or a clinician with substantial student debt whose income trajectory doesn’t look like that of a conventional borrower.
AHCU changed its underwriting to address this problem. Our mortgage products allow consideration of employment contracts for clinicians beginning roles within 60-90 days. And it uses more flexible treatment of student debt. Because we hold those loans in portfolio, it provides the latitude to create terms that conventional, secondary-market underwriting typically do not. The insight wasn’t that health care professionals needed another mortgage product with health care branding. It was that the underwriting itself needed to understand a health care career.
AHCU offers some unique financial services for the health care industry. What can you tell us about this?
Although we’re not a therapist, a social-service agency or a health care provider, we do believe we have a responsibility to recognize when the problem in front of someone extends beyond a deposit account or loan and connect them with resources or organizations that are better equipped to help. We have certified financial coaching resources, as well as trained financial service officers who can solve or optimize for most financial situations.
When more support is needed, FamilyMeans provides free budget and debt counseling through certified credit professionals, along with debt-management services and financial education. Its broader organization also provides counseling and mental-health services, grief and loss support, and aging and caregiver services.
TriUnity Foundation is another version of that principle. It’s a very new grant-making nonprofit built by the credit-union movement that provides direct grants to people facing life-threatening or terminal illness. For its current 2026 cycle, its program offers $2,500 and $10,000 grant pathways, and AHCU members are among those eligible. AHCU has a pool of grant dollars reserved specifically for its members.
If financial well-being is becoming a workforce issue, how should Minnesota health care organizations respond?
The best organizations include financial well-being as part of their workforce design, instead of an optional benefit topic. Compensation is obviously part of the equation, but so are things such as predictable scheduling, childcare considerations, emergency savings, student debt, career-development financing, access to trustworthy and relevant financial coaching as well as financial products that work with health care career paths.
A financial partnership can fill some of that gap. AHCU was created for Minnesota’s health care community, therefore, it has health care specific financial literacy and education content to present and share — including presentations earning CME credits. It develops products that meet the unique needs of health care professionals — including options for co-creating value with employers. We have locations in and near health care hubs, such as Children’s and United in St. Paul, with plans to be convenient throughout the Twin Cities’ health care corridors.
What can you tell us about the inroads bitcoin and blockchain technology are making into health care?
It’s important to separate Bitcoin from blockchain technology. Health care organizations need predictable values, strong privacy controls, regulatory compliance and a reliable settlement of funds. A highly volatile asset, such as Bitcoin, isn’t a strong fit.
About the Author
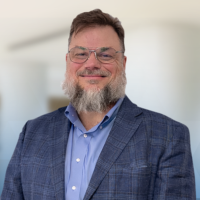
Joel A. Swanson
President/CEO
At AHCU, Joel is committed to expanding financial wellness for healthcare professionals and their families, while ensuring the credit union remains a trusted partner for Minnesota’s premier healthcare organizations, such as Allina Health, Blue Cross, Children’s Minnesota, and more. In addition, Joel serves on the board of the TriUnity Foundation, supporting individuals and families navigating the challenges of cancer and other terminal illnesses.
AHCU’s mission is personal for Joel, as he and his wife have four sons – each works in or supports healthcare.
We're Here to Support You
Personal Financial Coaching That Works for Your Life in Healthcare
Take Charge of Your Money with My Financial Pul$e
Track spending, connect all your accounts, and reach your goals faster—everything you need for smarter financial control in one place.
Join the Thousands of Healthcare Professionals Who Trust AHCU
You spend your days caring for others. We think you deserve a financial partner who cares for you.