
Fall Financial Reset: 5 Budgeting Tips to Promote Fiscal Health
Timely advice for healthcare workers – or any hardworking Minnesotan
Joel Swanson, President and CEO of Associated Healthcare Credit Union (AHCU), sees the pattern every year. “You can’t eliminate the pressures that come with working in healthcare,” he says, “but you can strengthen your financial foundations to give yourself more options.”
AHCU serves more than 12,000 members across Minnesota — nurses, technicians, caregivers, and others across the healthcare sector — as a not-for-profit credit union with locations inside hospitals and clinics. Swanson has perspectives both professional and personal: he has spent years in the health industry even before taking over as CEO last year, and all four of his sons work in the field.
What he sees and hears from members and peers confirms data that shows how challenging the finances of working people can be.
- A Federal Reserve report this year found that nearly six in 10 Americans experienced a major unexpected expense in the previous 12 months, and 37% said they couldn’t cover a $400 emergency with cash.
- A Becker’s Hospital Review analysis found that 30% of nurses have worked extra shifts due to financial strain, and 15% have taken a second job.
- A Mercer study found that 35% of healthcare workers say the cost of healthcare limits their ability to seek care for themselves or their families.
“The people who are giving care themselves feel limited in seeking care out for themselves or their families,” Swanson says. “To me, that’s crazy.”
5 Tips to Strengthen Your Finances
The tips Swanson offers are drawn from guidance AHCU provides its members, though the underlying principles apply broadly to anyone, especially hourly workers and those managing variable income.
1. Take Time to Look Back and Forward
Fall offers a natural vantage point: summer’s discretionary spending has wound down, and the final months of the year including holiday plans are coming into focus. Swanson recommends reviewing 60 to 90 days of financial activity — cash flow, emergency savings, high-interest debt, and credit health — and looking for trends before they become problems.
Are credit card balances increasing? Are savings goals being met? Have recurring subscriptions piled up? For healthcare workers in particular, Swanson suggests distinguishing between reliable base income and variable income from overtime. AHCU offers 30-minute financial checkups with a coach or advisor for members who want guidance.
2. Prepare for Expenses That Don’t Make the Back-to-School List
The obvious fall costs — school supplies, activity fees — are rarely the ones that derail a budget. It’s the surrounding expenses that catch people off guard: childcare gaps when college-age sitters return to school, travel costs for kids away at college, car maintenance before winter, and for healthcare workers, the fall continuing education cycle.
“A vehicle problem isn’t merely inconvenient when you have to report to a hospital before public transportation is operating,” Swanson says. A practical solution: build a 90-day expense forecast covering September through December, and begin funding those costs across several paychecks rather than absorbing them all at once.
3. Don’t Let Overtime Become Part of a Permanent Budget
Overtime and shift differentials can be a meaningful financial advantage — until they quietly become a financial necessity. Swanson sees this pattern frequently among healthcare workers who build recurring obligations around elevated pay, then find they can’t step back when burnout sets in.
His advice: keep base recurring expenses tied to base pay, and give overtime earnings a specific purpose before they arrive. He describes a simple three-bucket framework: some for tomorrow (savings and debt repayment), some for upcoming expenses, and some to spend now. “It doesn’t make you tied to a specific percentage,” he says. “You have some flexibility and direction.”
4. Build a Financial Breathing Room Fund
Rather than framing a reserve as an emergency fund — language that implies it can only be used for catastrophes — Swanson advocates for what he calls a breathing room fund. A cushion of even a few hundred dollars creates options: covering a childcare gap, car repair, or medical deductible without reaching for credit. It may also allow a healthcare worker to occasionally decline an extra shift.
“Let’s try to build up to $500,” he says. “Once we hit that, let’s build to $1,000, then one month of expenses.” Progressive milestones, he argues, make the goal achievable rather than abstract.
5. Use the Benefits Already Available (Especially Those that Expire)
Open enrollment is approaching, and year-end deadlines are coming for FSA dollars, HSA contributions, and unused tuition benefits. Swanson says many healthcare professionals leave these resources untouched. Employee assistance programs, which now often extend to eldercare referrals and legal services, are among the most overlooked.
Benefits can come from other sources, too. AHCU has also developed products specific to healthcare workers, including a mortgage launched this spring that treats professional student debt differently, allowing early-career workers — including nurses, not just physicians — to qualify sooner and borrow up to 100% of a home’s value.
Set the Next Year Up Right
Financial pressures on workers aren’t going away, and there is no silver bullet that will address every need faced by healthcare workers or anyone. But by being deliberate and aware of what is happening, making smart use of resources, and getting guidance from experts who have seen it all before, anyone can improve their situation.
“Financial resilience isn’t about having so much money that nothing goes wrong,” Swanson says. “It’s about creating enough room that when something does, you have more choices, so you can control what happens next.”
About the Author
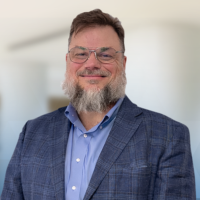
Joel A. Swanson
President/CEO
At AHCU, Joel is committed to expanding financial wellness for healthcare professionals and their families, while ensuring the credit union remains a trusted partner for Minnesota’s premier healthcare organizations, such as Allina Health, Blue Cross, Children’s Minnesota, and more. In addition, Joel serves on the board of the TriUnity Foundation, supporting individuals and families navigating the challenges of cancer and other terminal illnesses.
AHCU’s mission is personal for Joel, as he and his wife have four sons – each works in or supports healthcare.
We're Here to Support You
Personal Financial Coaching That Works for Your Life in Healthcare
Take Charge of Your Money with My Financial Pul$e
Track spending, connect all your accounts, and reach your goals faster—everything you need for smarter financial control in one place.
Join the Thousands of Healthcare Professionals Who Trust AHCU
You spend your days caring for others. We think you deserve a financial partner who cares for you.